An insurance check that falls short of a replacement purchase does not, by itself, explain whether the claim calculation is wrong. First identify how the policy values the damaged property and whether the payment is initial or final. Actual cash value and replacement cost answer different questions, and policy conditions determine what happens next.
Know what the terms measure
The National Association of Insurance Commissioners explains that actual cash value accounts for age and wear. Replacement-cost coverage generally measures the cost of repairing or replacing damaged property with comparable materials or items. Replacement cost is not the home’s real estate sale price, which also reflects land and market conditions.
Depreciation is the reduction attributed to age, condition or use. A deductible is the portion the policyholder bears under the policy. Neither term should disappear inside an unexplained total. Ask the adjuster to identify the estimated replacement amount, depreciation and deductible separately, along with relevant limits or exclusions.
Understand the possible second step
North Carolina’s Department of Insurance notes that insurers may initially pay actual cash value even under replacement-cost coverage. After repair or replacement and submission of receipts, additional reimbursement may follow; this is commonly called recoverable depreciation. The department emphasizes understanding how the particular policy pays. This explanation is not a promise about every claim.
Before ordering replacements, ask which depreciation is recoverable, what work or purchases qualify and what evidence the insurer requires. Confirm applicable completion and submission deadlines in writing. Also ask how the payment changes if an item is not replaced. Do not assume a rule from another state or a different policy applies.
Budget from the explanation
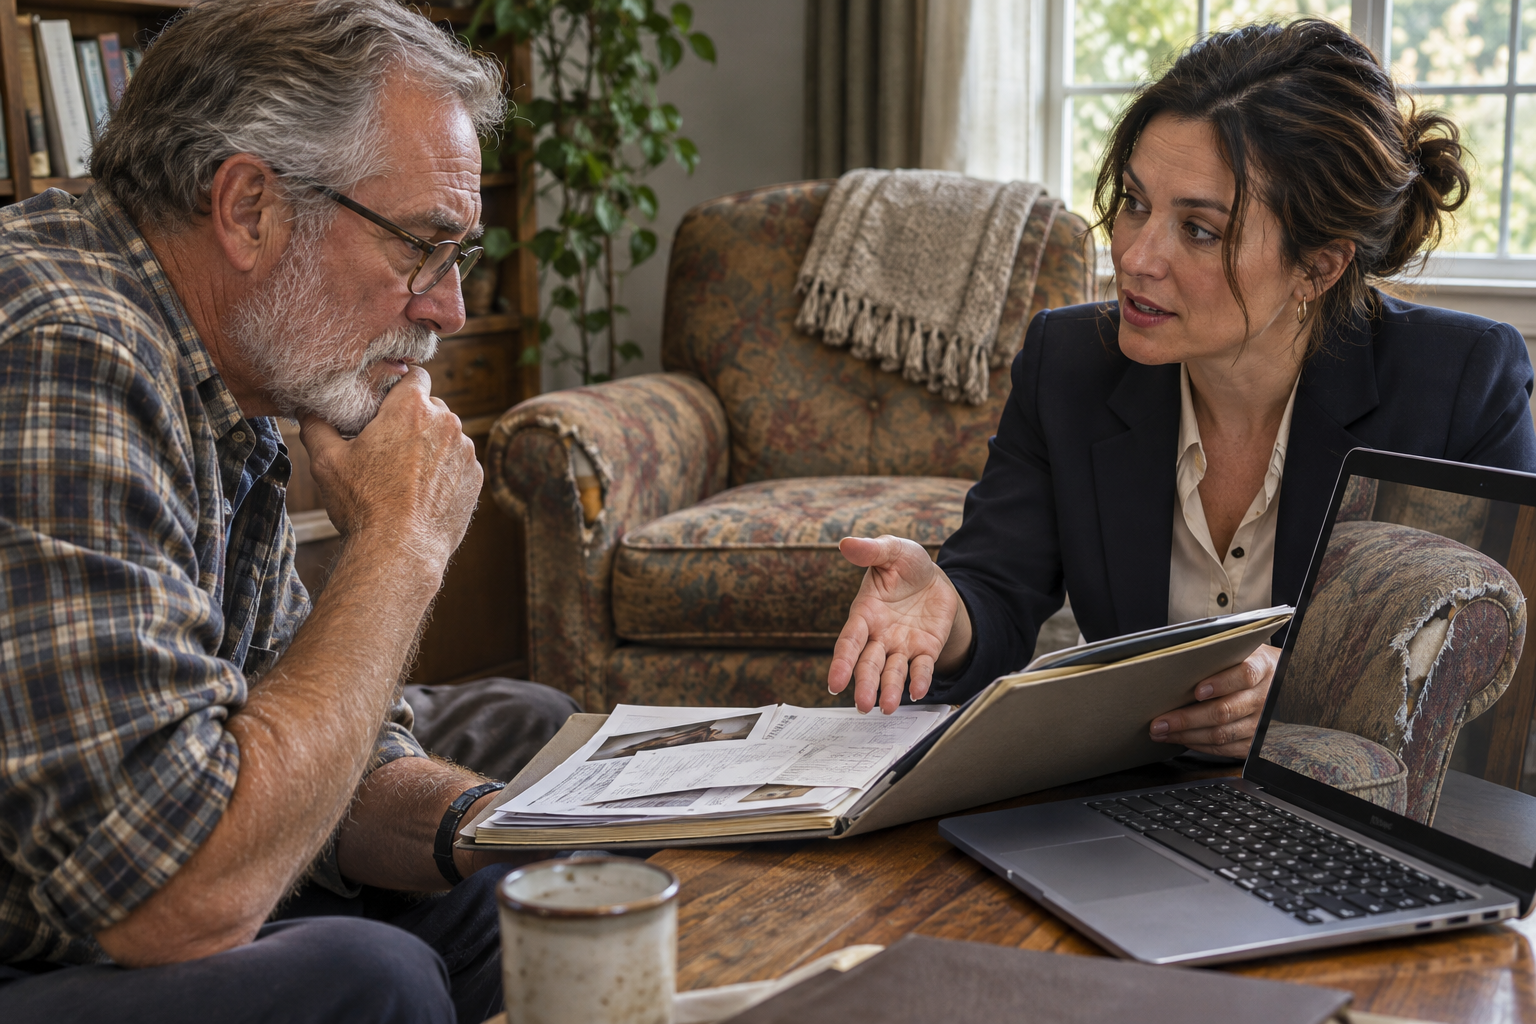
Consider a hypothetical homeowner replacing a damaged chair. The useful comparison is between the insurer’s valuation, comparable replacement options and the policy’s reimbursement conditions. Choosing a more expensive upgrade does not establish that the insurer must fund the difference. Keep receipts and ask questions before committing money based on an expected later payment.
Use NDR’s claim estimate comparison guide to separate repair scope from payment calculations. Request a written breakdown that shows what has been paid and what remains conditional. Keep each submission confirmation with the receipts supporting your request for reimbursement.
Prepared Nov. 6, 2026. General educational information based on linked regulator guidance, reviewed for this article. Coverage, valuation and claim procedures depend on the policy and applicable state rules. Examples are hypothetical.